Market Overview of the Casino Management Systems Market
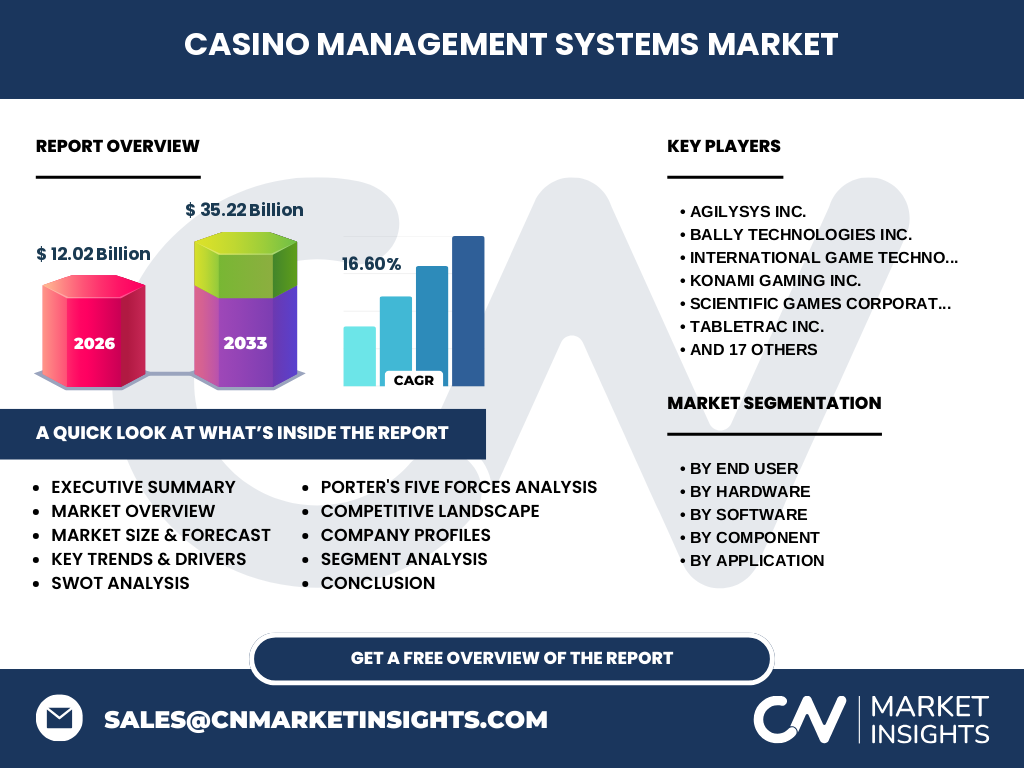
Our analysis indicates that the Casino Management Systems Market is valued at 12.02 Billion in 2026, encompassing integrated hardware like servers and payment devices alongside specialized software for player tracking and slot management, regulated by bodies such as the Nevada Gaming Control Board.
Structural Growth Drivers and Restraints
The market is propelled by a 16.60% CAGR driven by cashless gaming adoption, while strict compliance mandates from regulatory agencies like the UK Gambling Commission act as operational constraints requiring continuous software updates.
Emerging Trends in the Casino Management Systems Industry
Operators are rapidly deploying reporting and analytics software alongside advanced security solutions from innovators like Avigilon Corporation to transition from legacy pit tracking to real-time player behavior intelligence.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-era closures severely disrupted floor operations, forcing operators to accelerate contactless payment processing devices and remote server management to comply with social distancing mandates enforced by regional health authorities.
Competitive Benchmarking and Market Dynamics
The landscape features key innovators like International Game Technology PLC and Aristocrat Technologies Australia Pty Ltd competing fiercely, balancing proprietary hardware ecosystems with modular software integrations to capture enterprise-level contracts.
Executive Summary of Casino Management Systems Industry Trends
Driven by digital transformation, the Casino Management Systems Market will scale dramatically from its 2026 baseline, fueled by surging demand for automated accounting, cash management, and targeted marketing promotions across global gaming jurisdictions.
Long-Term Market Forecast from 2027 to 2033
Our research forecasts the market will expand from 2027 to reach 35.22 Billion by 2033, representing a robust 16.60% CAGR underpinned by widespread infrastructure modernization in emerging entertainment hubs.
Segmentation Analysis Across Hardware and Software
The market bifurcates into hardware categories including networking equipment and workstations, and software segments featuring casino management and table game management software, tailored to optimize both small venues and massive casino resorts.
Regional Market Analysis and Geographic Distribution
North America commands the largest market share due to mature regulatory frameworks, while the Asia-Pacific region exhibits high growth potential driven by mega-resort developments requiring comprehensive surveillance and analytics integration.
In-Depth Regional Review of Operational Constraints
Regional performance is heavily dictated by local compliance; for instance, European markets navigate stringent data privacy laws impacting player tracking software, while US operations focus heavily on anti-money laundering reporting compliance.
Company Profiles and Strategic Positioning
Industry leaders such as Agilysys Inc., Scientific Games Corporation, and Playtech PLC leverage strategic acquisitions and modular software deployment to solidify their dominance across both land-based and online hybrid gaming sectors.
Porter's Five Forces Analysis of the Gaming Tech Sector
Bargaining power of buyers remains moderate due to high switching costs associated with enterprise-grade server migrations, while threat of new entrants is low given strict licensing requirements imposed by global gaming commissions.
SWOT Analysis of the Casino Management Systems Market
Strengths lie in real-time operational visibility, whereas weaknesses involve high upfront hardware capital expenditures. Opportunities abound in AI-driven marketing promotions, countered by threats from sophisticated cyber threats targeting payment processing devices.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from silicon semiconductor suppliers and metal casing manufacturers for terminals, through OEM assembly by firms like Panasonic Holdings Corporation, culminating in direct deployment at large and small casino end-users.
Investment Insights and High-Potential Areas
Investors should target developers of cloud-native reporting and analytics software and advanced security applications, as these segments offer the highest recurring revenue potential within the expanding Casino Management Systems Market ecosystem.
Conclusion and Strategic Key Takeaways
The path forward requires vendors to prioritize interoperability and robust cybersecurity, ensuring their platforms seamlessly bridge legacy slot machines with modern digital wallet payment infrastructures for sustained profitability.
Research Methodology and Baseline Estimation
Our baseline estimates are triangulated by combining trade registry data from gaming commissions, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators influencing discretionary leisure spending.
Scope of the Report and Coverage Parameters
This report covers global deployment metrics across hardware, software, and end-user segments from 2026 to 2033, explicitly excluding illegal underground gambling networks and focusing solely on legally licensed commercial and tribal gaming operations.
Recent Developments and Strategic Industry Moves
Recent strategic moves include partnerships between biometrics innovators like NtechLab LLC and major surveillance providers to integrate facial recognition directly into existing casino security software frameworks for enhanced patron vetting.